Hawkmen Insights
Business AcquisitionsHow Lenders Look at a Self-Storage Facility Acquisition
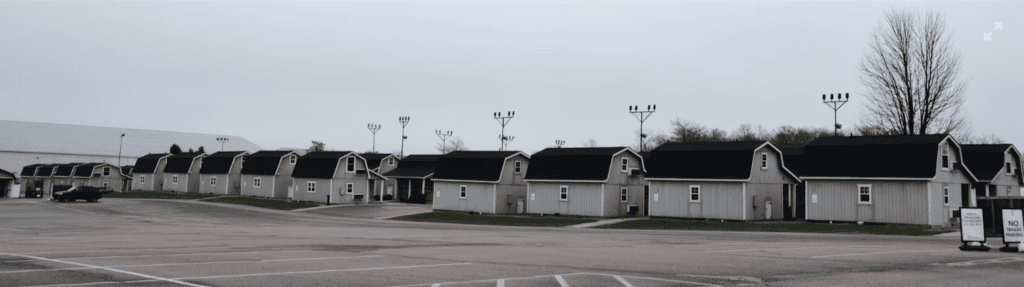
Self-storage has become one of the more sought-after acquisition targets in commercial real estate. Low staffing requirements, diversified tenant bases, and historically resilient occupancy make the asset class attractive to buyers moving up from residential or smaller commercial properties. From a lender’s perspective, however, a self-storage facility is underwritten on its own terms — and a strong-looking property can still produce a weak financing request if the file doesn’t answer the right questions.
How Lenders Verify Self-Storage Income
Revenue verification is the starting point. Self-storage income typically comes from unit rents, administrative and late fees, tenant insurance or protection plans, truck rental commissions, and sometimes retail sales of boxes and locks. A lender will want to see this broken out clearly — not blended into a single “gross income” line — and reconciled against a current rent roll, trailing 12-month operating statement, tax returns, and bank deposits.
Occupancy history matters as much as current occupancy. A facility sitting at 92% today tells a lender very little without seeing where it was 12 and 24 months ago, and why. Seasonal swings, a recent rate increase, a nearby competitor opening, or a one-time bulk-tenant move-out can all explain a snapshot number that looks better or worse than the underlying trend.
Why the Rent Roll Gets Read Line by Line
Unlike a laundromat or a single-tenant business, a self-storage facility has dozens or hundreds of individual leases. Lenders will look closely at unit mix (standard, climate-controlled, vehicle/RV, outdoor), in-place rents versus street rents, average length of stay, delinquency and lien/auction activity, and how much of the rent roll is on month-to-month terms versus longer commitments. A wide gap between in-place and street rents can be a real upside story — or a sign that management has been slow to push rates, which raises its own questions about operating discipline.
Not sure how a lender may view your deal? Start with the 60-Second Funding Snapshot.
Get Your Funding Snapshot
Expense Load and Deferred Maintenance
Self-storage is often marketed as “low expense,” and relative to other commercial real estate it can be. But lenders still expect a realistic expense picture: property taxes at the post-sale assessed value (not the seller’s often-lower basis), insurance, on-site or remote management costs, gate and camera system maintenance, paving and fencing condition, and any deferred capital items like roofing, door replacement, or climate-control equipment. A facility that has been under-maintained to inflate seller cash flow will show up in a property condition report, and the buyer should budget for it before it becomes a surprise after closing.
Why Location and Competition Still Decide the Deal
Self-storage is a supply-sensitive asset class. A lender will want to understand the trade area’s population density, household turnover, new construction pipeline, and how many competing facilities exist within a reasonable drive time — along with their unit mix and pricing. A facility that looks strong in isolation can be far less attractive if three new climate-controlled projects are under construction two miles away. The buyer should be prepared to speak to this directly, not just point to current performance.
Structuring the Purchase
Most self-storage acquisitions involve both real estate and, in some cases, an operating business component if third-party management, retail sales, or ancillary services are significant. The purchase structure should clearly separate real property value, personal property (gates, cameras, office equipment), and any goodwill or business value. If a management contract or franchise/brand affiliation is part of the deal, the lender will want to understand what happens to that relationship post-closing.
Borrower Experience and Post-Closing Liquidity
Direct self-storage ownership experience helps, but it isn’t the only path to approval. Relevant backgrounds in real estate investing, property management, or operating other cash-flowing commercial assets can support the file when paired with a credible plan — who manages the facility day to day, how rate increases will be handled, and what the marketing and lease-up strategy looks like if occupancy needs to improve. Lenders also look past the purchase price to the buyer’s remaining liquidity after closing costs, reserves, and any near-term capital needs. A buyer who is fully drawn down at the closing table has less room to absorb a slow season or an unexpected repair.
The strongest self-storage acquisition files combine a verified income trail, a rent roll that’s been read line by line, a realistic expense and capex picture, and a buyer who can speak to competition and operations — not just the trailing NOI.
Ready to prepare your financing request?
Know Before You Apply™ — $27
Free Commercial Deal Readiness Check™
Related insights
Hawkmen Enterprises is a commercial capital advisory firm and is not a lender. Financing availability, terms, leverage, rates, and approval depend on the borrower, transaction, documentation, lender requirements, and underwriting.